
Federal data shows car insurance prices easing, down 4.5% over the twelve months ending July 2026. That does not reach your policy on its own, and after prices rose 17.4% in 2023 and 17.8% in 2024, “I will deal with it at renewal” is an expensive habit. So here are five moves that can change your bill this week, with no six-month monitoring period. For the full list of levers, see our complete guide to lowering your rate. If you want the bill smaller by Friday, start here.
| Move | Time | Typical impact |
|---|---|---|
| 1. Get three competing quotes | 20-40 min | Largest single lever; state insurance departments publish comparisons showing wide gaps between carriers |
| 2. Raise your deductible | One call | Varies by carrier; ask for the quoted difference |
| 3. Claim discounts you already earn | Same call | Low single digits, stacked |
| 4. Run the 10x test on older cars | 5 min | Can remove a large share of that vehicle’s bill |
| 5. Reclassify your mileage | Same call | Varies; meaningful if your commute shrank |
1. Get three quotes at identical coverage
This is the move that outweighs the other four combined, and it works this week because new-business pricing is where carriers put their sharpest numbers. Several state insurance departments publish official premium comparison tools built from filed rates, and the spread between carriers quoting the same driver profile is routinely wide enough to matter. The rules that make it work: identical liability limits, identical deductibles, identical drivers listed. Change any of those and you are no longer comparing the same policy. If the winning quote beats your renewal, schedule the switch for your renewal date so there is no lapse. A lapse of even a few days gets priced as risk for years; a clean switch at renewal costs nothing.
2. Raise your deductible on the same call
Moving collision and comprehensive from $500 to $1,000 shifts more of each claim onto you, and the premium comes down in proportion. Most carriers apply it immediately, prorated on your current term. How much it saves depends on the carrier and the state; get the actual quoted difference first. The one-question test before you do it: could you cover the extra $500 tomorrow without a credit card? If yes, you are paying the insurer to hold risk you could carry yourself. If no, skip this one. A deductible you cannot afford turns a bad day into debt.
3. Audit the discounts you already qualify for
While you are on the phone: pay-in-full (a real discount at most carriers, and it also deletes the installment fees hiding on your bill), paperless and autopay, good student if you have a driver under 25 with a B average, and any defensive driving course you completed. None of these changes your life on its own. Together they can shave a real percentage, and you may already qualify for them without getting them because nobody asked. Carriers do not volunteer discounts. From my years on the marketing side, I can tell you the budget goes to winning new customers, not to telling existing ones what they are missing.
4. Run the 10x test on any car past its prime
Look up your older car’s market value, then look at what you pay annually for collision and comprehensive on it. If the car is worth less than ten times those coverages, you are paying premium prices to protect a depreciated asset, and the maximum the policy can ever pay you is the car’s value. Dropping collision and comprehensive on a paid-off, low-value car can be the single biggest line-item cut available on that vehicle. Keep liability. Never do this on a financed or leased vehicle; your lender requires full coverage.
5. Reclassify how much you actually drive
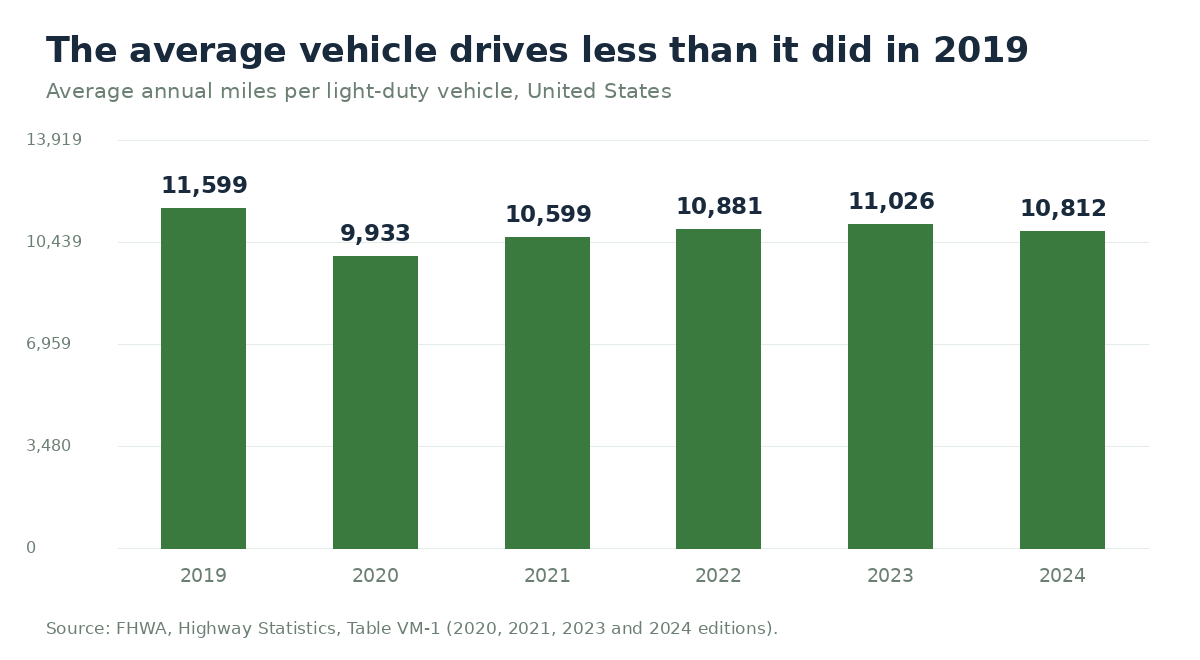
Your policy has a mileage estimate on file, and if it predates a remote-work shift, a retirement, or a shorter commute, you may be rated as a commuter you no longer are. The federal baseline sits lower than most people assume. FHWA Highway Statistics puts the average light-duty vehicle at 10,812 miles in 2024, down from 11,599 in 2019, and the figure has stayed under 11,100 every year since 2020. Many quote forms default to a 12,000 or 15,000 mile band unless someone changes it, which can leave a thousand miles or more of assumed driving on your record. Ask what annual mileage is on file, then check it against two odometer readings twelve months apart. If you really drive under roughly 7,000 miles a year, also ask about low-mileage programs, but read the fine print first; the tracking-app version of that discount has trade-offs we cover in our usage-based insurance guide.
The 20-minute quote process that actually works
Speed matters this week, so here is the process stripped to essentials. Pull your current declarations page, the one or two page summary your carrier mailed or posted in your account portal; it lists your exact limits, deductibles, and drivers. Quote against it verbatim at two direct carriers and one independent agent or comparison site. Have ready: driver’s license numbers, VINs, and your current policy’s limits. Decline every checkbox upsell during quoting so the numbers stay comparable, and write down each quote’s annual total rather than the monthly teaser, because monthly displays hide installment fees. In twenty minutes you have three real numbers and know whether your renewal is competitive or just counting on you not to look.
The script for the phone call
Moves two, three, and five happen in one call. The exact wording matters less than the order. Ask in this order: “Can you review my policy for any discounts I qualify for but do not have?” Then: “What would my premium be with collision and comprehensive at a $1,000 deductible?” Then: “What annual mileage do you have on file for me?” Each question makes the rep look something up instead of reading from a script. If you have a competing quote in hand, say so plainly at the end: “I have a quote from [carrier] at [number] for the same coverage. Is there anything you can do on price?” Retention teams exist precisely for that sentence, and they have levers front-line billing reps do not. If the answer is no, you lost nothing, and now you know to switch.
What not to do this week
Do not cut liability limits to state minimums to force the number down. It saves money and exposes everything you own to one bad left turn. In most states the minimum will not come close to covering a serious hospital bill. And do not cancel mid-term without the replacement policy already active. The savings play is a clean switch, never a gap. If your rate feels inexplicable in the first place, the mechanics are not personal, and we explain them in why your rate went up with a clean record.
What these five moves cannot fix
One limit: if your renewal spiked because of a recent at-fault accident, a DUI, or a major violation, these moves still help but they cannot erase a surcharge, and nothing legitimate can. What you should know instead: surcharges age off, typically in three to five years depending on your state and carrier, and surcharged drivers see the widest price spread of anyone in the market, because each carrier penalizes the same incident very differently. You can see it in the surcharge schedules in every state’s approved rate filings. So shopping matters more after an incident, not less. Get the three quotes anyway, expect higher numbers, and put your renewal date on the calendar for the year the surcharge ages off, because that renewal is when shopping again pays off most.
Quick answers
Will these changes take effect before my renewal?
Deductible changes, discount additions, and mileage corrections apply mid-term with most carriers, prorated. Carrier switches are cleanest at renewal.
Does getting quotes hurt my credit?
Insurance quotes use a soft pull for credit-based insurance scoring in states that allow it. It does not affect your credit score the way a loan application does.
Which of the five matters most?
The quotes. The other moves adjust your current carrier’s pricing. Shopping can replace it entirely. Do it first, then make the other four calls to whoever wins.
Can my carrier raise my rate because I asked these questions?
No. Your rate was filed with your state before your renewal printed; questions, discount requests, and quote shopping do not change it. The only self-inflicted increase available here is letting coverage lapse during a switch.
Savings vary, and none of these figures is a guarantee. Your state, carrier, vehicle and profile set your actual numbers, so get each one quoted on your own policy before you act.

Sources
4
Every figure in this article traces to a government record or to a named independent, non-commercial research body. We do not cite insurance marketplaces or affiliate comparison sites for data.
- U.S. Bureau of Labor Statistics Consumer Price Index, July 2026 Published 2026-08-12Supports: Motor vehicle insurance index down 4.5% over the twelve months ending July 2026
- U.S. Bureau of Labor Statistics Consumer expenditures in 2024 Published 2025-12-19Supports: Vehicle insurance prices rose 17.4% in 2023 and 17.8% in 2024
- Federal Highway Administration, U.S. Department of Transportation Highway Statistics, Table VM-1, Annual Vehicle Distance Traveled in Miles and Related Data Published 2026-02Supports: Average miles traveled per light-duty vehicle (short wheelbase): 11,599 in 2019, 9,933 in 2020, 10,599 in 2021, 10,881 in 2022, 11,026 in 2023, 10,812 in 2024. Figures taken from the 2020, 2021, 2023 and 2024 editions of Table VM-1, each edition being the most recent publication of that year
- California Code of Regulations / California Department of Insurance 10 CCR 2632.5(c)(2), auto rating factor regulations under Proposition 103Supports: Credit-based insurance scoring is prohibited as a personal auto rating factor in some states, which is why the credit question in the FAQ is state-dependent
Figures last verified August 29, 2026.